Director liability in group structures: a high threshold, but not insurmountable
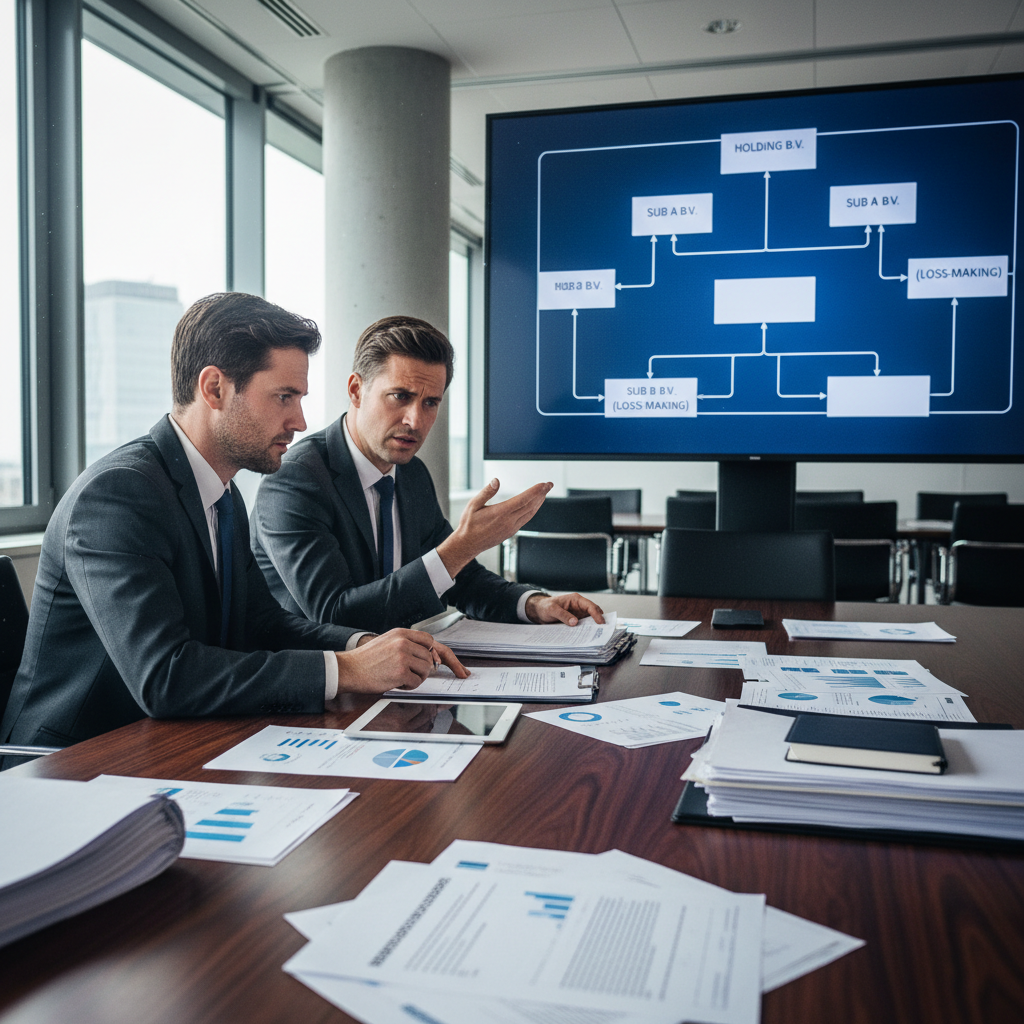
Within group structures, profits and costs are often strategically distributed across different companies. This is, in itself, permitted. But when a company is structurally made loss-making to benefit other group entities, leaving creditors empty-handed, the director may face personal liability.
The Amsterdam Court of Appeal confirmed this on 28 October 2025 in a notable judgment (ECLI:NL:GHAMS:2025:2851). Not a liquidator, but a minority shareholder and creditor successfully held the director personally liable — on three separate grounds.
The facts: from share sale to loss-making 'loss subsidiary'
Istia B.V. had sold a controlling interest in Qlog B.V. — a transport start-up — in 2018 to Tow Invest B.V., part of a group of which the director (appellant) was the sole shareholder and director. The purchase price was to be paid through a per-kilometre fee: Qlog would henceforth drive for the group and use the proceeds to repay its debt to Istia. Tow Invest provided a surety and guarantee for this purpose.
In practice, things turned out very differently:
- Qlog drove kilometres for the group but received no cost-covering fee.
- Trucks and personnel were gradually transferred to other group companies.
- Qlog became structurally loss-making while the revenues from its activities flowed to other group entities.
- On the repayment date of 1 February 2020, nothing had been paid.
- When Istia sought recovery from Tow Invest (under the surety), that company turned out to be empty and already dissolved.
- Shortly thereafter, Tow Invest filed for Qlog's bankruptcy.
Istia sued the director personally on three grounds.
Three grounds for personal liability
1. Wilful non-payment (frustration of recovery)
The standard from Ontvanger/Roelofsen (Supreme Court, 8 December 2006) provides that a director can be personally liable if he brings about a situation in which the company fails to meet its obligations and offers no means of recovery. The court held that this was the case: other creditors were paid while Istia was deliberately not paid. Assets were also removed from Qlog, making recovery impossible — and Tow Invest was dissolved almost immediately after a judgment against it. The timing was telling: deliberate frustration of recovery.
2. Violation of the Beklamel standard
The Beklamel standard (Supreme Court, 6 October 1989) holds that a director is personally liable if he enters into an obligation on behalf of the company while knowing or having to understand that the company would not be able to fulfil it and would offer no means of recovery.
Here, the director had provided a surety and guarantee on behalf of Tow Invest to Istia — while Tow Invest was an empty company with no assets. He knew, or should have known, that the surety was meaningless. By providing this guarantee, he created the impression that security existed when in reality it did not.
3. The Comsys standard: special duty of care for a loss-making subsidiary
This is the most notable ground. In the Comsys ruling (Supreme Court, 11 September 2009), the Dutch Supreme Court recognised that a parent company may have a special duty of care towards creditors of a loss-making subsidiary when the group structure results in those creditors being harmed.
The court found that Qlog structurally worked below cost price for the group. All costs sat with Qlog; revenues flowed to other group companies. That is not prohibited in itself — but it does give rise to a special duty of care: the director should have ensured that Istia's claim was satisfied by other means. The surety and guarantee provided could have served that purpose, but led to nothing. The duty of care was therefore not met.
The court upheld the first-instance judgment: the director is personally liable for the damage Istia suffered.
Notable: a creditor and minority shareholder wins
What makes this judgment particularly interesting is that it was not a liquidator (with broad access to company records) who brought the claim, but Istia itself — as a creditor and minority shareholder. That makes the threshold to succeed considerably higher. Yet Istia succeeded in establishing all three grounds, in part because the facts were well documented through the shareholder relationship.
What does this mean in practice?
As a director or DGA in a group context:
- A group structure in which a subsidiary is structurally made loss-making to benefit the parent or sister companies is not automatically prohibited, but gives rise to a special duty of care towards creditors of that subsidiary.
- Ensure that creditors of a loss-making subsidiary can actually recover — through the surety, guarantee, or otherwise. An empty guarantee is worse than no guarantee at all: it creates trust that is not honoured.
- The timing of liquidations and bankruptcy filings matters: a dissolution shortly after a judgment is treated as deliberate frustration of recovery.
- Selective payment (paying other creditors but not a specific one) significantly increases the risk of personal liability.
In group restructurings and asset transfers:
- Transferring trucks, staff or contracts to other group companies may be characterised as frustration of recovery, particularly where creditors of the remaining company are harmed.
- When setting internal pricing arrangements (transfer pricing), take into account the interests of creditors of each individual group company.
Conclusion
The Amsterdam Court of Appeal's judgment of 28 October 2025 powerfully confirms that directors in group structures cannot escape liability when they harm creditors through internal structural choices. The combination of frustration of recovery, an empty surety, and a loss-making group structure resulted in personal liability on three separate grounds. Directors would do well to assess, when designing group structures, whether creditors of loss-making subsidiaries can actually recover — and, if not, to intervene in time.
Ruling
This blog post is based on ECLI:NL:GHAMS:2025:2851, judgment of the Amsterdam Court of Appeal of 28 October 2025.
Do you have legal questions following this ruling?
Mr. Vincent Besters is happy to help. Contact us for a no-obligation first consultation.
Get in touch →